Source: Adobe Stock
Switzerland Must Make UBS Safer – Not Weaker
I believe Switzerland must draw the right lessons from the collapse of Credit Suisse.
UBS is now so large in relation to the Swiss economy that stronger safeguards are unavoidable. Another banking crisis would cause far greater damage to Switzerland’s reputation than any additional capital requirement. But there is also a danger of overreaction.
If UBS is subjected to rules that are substantially tougher than those faced by its international competitors, it could reduce activities, move business abroad or become less willing to invest and grow from Switzerland. The consequences would extend beyond UBS, affecting talent, innovation and the international reach of the entire financial centre.
Most Intelligence Balance
The challenge is therefore not to choose between safety and competitiveness. Switzerland needs both. Regulation should make UBS demonstrably more resilient without placing it at a permanent global disadvantage. In my view, the country’s credibility will ultimately depend not on imposing the toughest possible rules, but on finding the most intelligent balance.
So far, however, there appears to be little genuine willingness to find that balance. For months – indeed, almost years – an unusually explicit disagreement has persisted between UBS’s top management and the Swiss government, as well as the SNB and FINMA. The positions have hardened, while a mutually acceptable solution still seems remote.
In Sharp Contrast
This stark confrontation stands in sharp contrast to Switzerland’s traditional culture of consensus and pragmatic compromise. The Swiss approach has generally been to find solutions that all sides can bear and that ultimately strengthen the country as a business and financial centre.
The apparent inability – or unwillingness – to do so in this case is highly unusual for Switzerland. More importantly, it risks turning a necessary regulatory reform into a prolonged dispute that could itself damage the financial centre both sides claim to protect.
Source: Adobe Stock
Pictet’s Lesson in Asia: Access is the New Alpha
A Swiss investment fund tripling in size to more than $5 billion is impressive under any circumstances. But what makes the rapid growth of Pictet’s Strategic Income Fund particularly interesting to me is where the money is coming from.
Around 60 percent of the fund’s assets reportedly originate from Chinese investors using the Mutual Recognition of Funds programme linking Hong Kong and mainland China, according to news wire Reuters this week.
The fund offers exposure to assets such as US government bonds, gold and leading global technology companies. Its performance has undoubtedly helped attract investors. But I believe the more important story lies beneath the investment results.
In other words: Swiss private bank Pictet has found an effective, legally recognised channel through which Chinese investors can gain international exposure at a time when access to offshore investments is becoming more closely controlled.
The Product Alone Is No Longer Enough
For decades, Swiss banks expanded internationally by exporting the traditional private-banking model. They opened representative offices, hired relationship managers and encouraged wealthy clients to book assets in Switzerland, Singapore or Hong Kong. That model remains relevant, but it is no longer the only route to growth.
Pictet’s success demonstrates that a Swiss wealth manager can reach Asian investors without depending exclusively on the classic offshore relationship. The company is combining Swiss investment expertise with local regulatory access and an established distribution infrastructure. In my view, this combination may be just as important as the underlying portfolio.
Distribution Becomes a Strategic Advantage
We often discuss performance, product innovation and the quality of investment advice. Yet even an excellent product has limited value if the intended clients cannot conveniently or legally access it. In Asia’s increasingly regulated and fragmented markets, distribution architecture is therefore becoming a genuine competitive advantage.
This is particularly relevant in China, where demand for international diversification remains strong but the available channels are carefully controlled. Investors are looking for exposure to global bonds, gold and technology stocks, while regulators want capital to move through transparent and approved structures. The Mutual Recognition of Funds programme brings these interests together – and Pictet appears to have positioned itself intelligently within that framework.
Broader Lesson for Swiss Wealth Management
To me, this is more than a successful fund story. It is a lesson in how Swiss wealth management can compete in Asia’s next phase. The winners may not necessarily be the institutions with the largest offshore booking centres or the greatest number of relationship managers. They may be those that understand how regulation, distribution, technology and investment expertise must work together.
Swiss wealth managers still possess a powerful international reputation. But reputation alone will not secure future growth. They must make their expertise accessible through the structures Asian clients can – and want to – use. Pictet’s $5 billion fund shows what can happen when a strong product meets the right regulatory bridge at precisely the right moment.
Source: AI tool
Beyond Banking: How Hong Kong and Singapore Compete for the World’s Wealthy
The contest for Asian wealth is no longer fought only through products, performance and relationship managers. It is increasingly a competition between complete destinations.
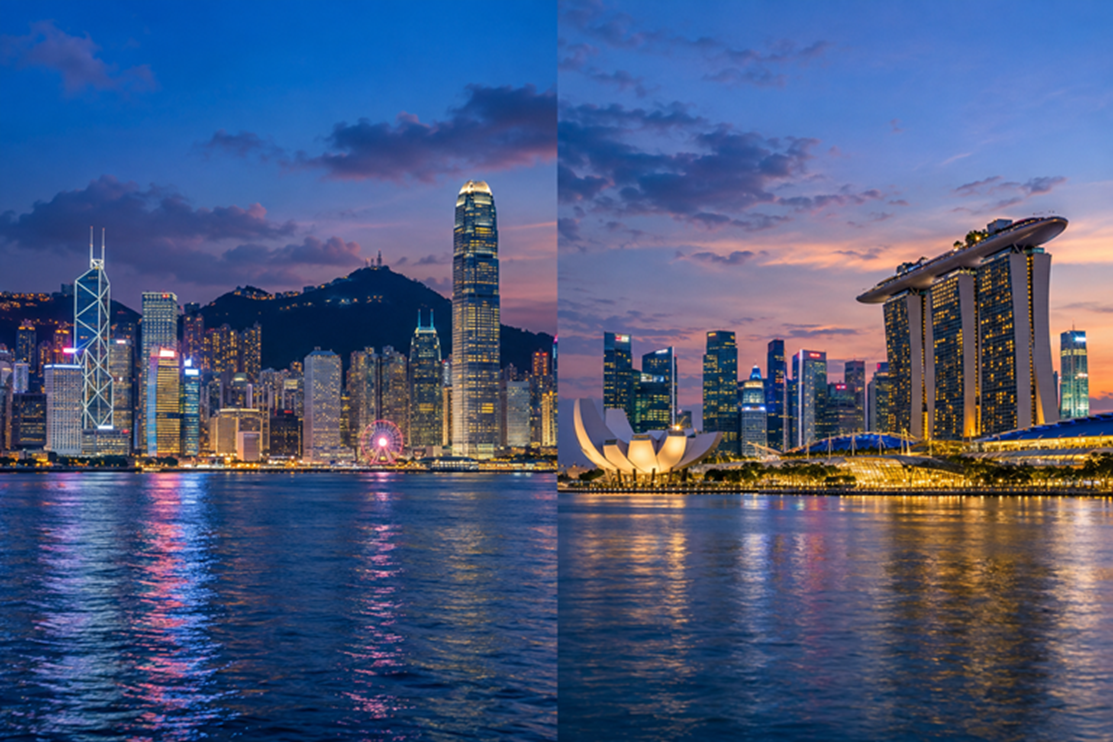
Hong Kong wants to become more than a place where international wealth is managed. Under its first Five-Year Plan for 2026-2030, the city is combining tourism, culture, sport, finance and lifestyle to strengthen its appeal to visitors, investors and internationally mobile families.
The strategy includes more major cultural and sporting events, expanded venues, film-production support and new tourism partnerships with mainland China, according to a recent media release. Hong Kong received 36.67 million visitors during the first eight months of 2026 – an 11 percent increase – and more than 20 percent of its overseas visitors continued into mainland China during the first half of the year.
Destination is Part of the Financial Proposition
This matters to wealth management because wealthy clients do not select financial centres on banking expertise alone. They also consider connectivity, culture, education, property, leisure opportunities and the quality of life available to their families. Hong Kong’s plans for marinas and cross-border yacht travel within the Greater Bay Area show how deliberately it is developing this wider ecosystem.
Singapore is pursuing a comparable strategy. It combines political stability, efficient infrastructure and global connectivity with major events, luxury hospitality, MICE and new tourism developments. Singapore generated record tourism receipts of S$32.8 billion in 2025, with business-event visitors making an increasingly important contribution.
Two Gateways, Two Different Strengths
The competition is becoming increasingly sophisticated. Hong Kong offers unrivalled access to mainland China and the Greater Bay Area, supported by a resurgent capital market. Singapore positions itself as the stable, technology-friendly gateway to Southeast Asia and an attractive base for entrepreneurs, family offices and multinational businesses.
For banks and wealth managers, the lesson is clear: the contest for Asian wealth is no longer fought only through products, performance and relationship managers. It is increasingly a competition between complete destinations.
The financial centre that offers the most convincing combination of capital, opportunity, connectivity and lifestyle will have the stronger claim on the next generation of global wealth.
Source: Adobe Stock
Five Lessons for Swiss Banking
Singapore treats wealth management as a national growth industry. Switzerland still regards it largely as an established strength to be protected and regulated. That difference in mindset could determine which financial centre attracts the next generation of global wealth.
Singapore aligns the essential elements of its strategy: tax policy, immigration, regulation, public investment, technology, talent development and international promotion. Its recent package for fund managers illustrates this approach. Tax incentives, a hedge-fund investment programme and easier visa rules all serve the same objective – attracting firms, capital, talent and decision-makers.
The Monetary Authority of Singapore (MAS) therefore acts not only as a regulator, but also as an architect of the financial ecosystem. It supervises the industry while helping to create the conditions for its future growth.
Singapore Builds While Switzerland Defends
Switzerland operates differently. Responsibility is divided among the federal government, FINMA, the cantons, industry associations and individual institutions. This decentralisation has advantages, but it rarely produces a coherent national direction.
Since the collapse of Credit Suisse, the Swiss debate has understandably focused on capital requirements, supervision and systemic risk. These issues are necessary, but they have left Switzerland looking defensive at precisely the moment when Singapore is building aggressively for growth.
The Comfort of Accumulated Success
Switzerland may also be suffering from the comfort of accumulated success. It continues to manage vast volumes of international wealth and remains synonymous with stability, expertise and discretion. But yesterday’s assets do not guarantee tomorrow’s inflows.
Singapore is positioning itself for newly created Asian wealth, internationally mobile entrepreneurs and families establishing professional family offices. It is not merely defending what it has; it is designing the financial centre it wants to become.
Five Priorities for a New Swiss Strategy
A credible Swiss strategy should, in my view, rest on five priorities.
1. Redefine Swiss Confidentiality
Switzerland cannot – and should not – return to traditional banking secrecy. But it can become the world’s most trusted jurisdiction for legally compliant financial privacy, cybersecurity and responsible data governance. The debate surrounding the beneficial-ownership register demonstrates how important this distinction has become.
2. Lead in Complex Wealth
Switzerland should compete less on portfolio management alone and more on the difficult questions surrounding wealth: succession, family governance, cross-border structuring, entrepreneurial liquidity events, philanthropy and private-market holdings. These are areas in which human judgement remains indispensable and fees are less easily commoditised.
3. Build an Open Wealth Ecosystem
Banks, external asset managers, family offices, fintechs, lawyers and other specialists should be able to collaborate through interoperable platforms. Tomorrow’s clients will work with several providers. Switzerland’s opportunity is therefore not to “own” every client relationship, but to become the world’s most trusted orchestrator of complex wealth.
4. Connect Talent, Innovation and Finance
Switzerland needs easier access to specialists in artificial intelligence, digital assets, cybersecurity and international wealth planning. Its regulatory framework should also permit controlled experimentation with tokenisation, digital custody and AI-supported advice. Singapore treats innovation and financial-centre policy as parts of the same strategy; Switzerland still tends to address them separately.
5. Compete for the Next Generation of Wealth
A national strategy must address both inherited and newly created wealth. NextGen clients expect global access, digital convenience, compelling investment opportunities and specialist advice – without becoming dependent on a single institution. Switzerland should design its proposition around these emerging behaviours rather than around yesterday’s client segments.
Structure, Govern, and Deploy Wealth
The fundamental difference is one of posture. Singapore asks how it can attract the next trillion. Switzerland too often asks how it can preserve the trillions already there. A successful strategy must do both.
Switzerland does not need to imitate Singapore. Its stronger proposition would combine Swiss stability and institutional depth with a more open, technologically capable and client-centred ecosystem.
Its future lies not merely in remaining the safest place to store wealth, but in becoming the best place to structure, govern and deploy it.
Source: Adobe Stock
Revolut Wants to Become Swiss – Should the Banks Be Worried?
Revolut’s application for a Swiss banking licence is much more than another fintech expansion. In my view, it represents a direct challenge to Switzerland’s established banks.
What exactly is Revolut? Founded in London in 2015, it began as a technology-driven financial platform offering low-cost currency exchange and international payments through a mobile app.
It has since expanded into accounts, cards, savings, investments, cryptocurrencies and business services. With around 80 million clients globally, it is now seeking to transform itself from a useful financial app into a fully fledged international digital bank, according to news wire Reuters.
Serious Swiss Ambition
Revolut plans to invest more than 150 million francs in Switzerland and establish a locally regulated bank. A Swiss licence would allow it to offer local IBANs, salary accounts, investment accounts in francs and Swiss deposit protection. It also intends to triple its Swiss workforce by the end of 2027.
This is the decisive step. Until now, many Swiss clients have used Revolut as a supplementary provider – particularly for travel, foreign-exchange transactions and online payments. A domestic banking licence would give it the credibility and infrastructure to compete for salaries, savings and investments. In other words, Revolut wants to move from the edge of the relationship to its centre.
NextGen Is Already Voting With Its Smartphone
Revolut claims approximately 1.3 million Swiss customers, equivalent to nearly a quarter of its addressable market. That should make traditional banks take notice. The platform’s rapid adoption reflects a behaviour we also identified in WealthSummit’s NextGen research: emerging wealth holders are comfortable using several providers and selecting whichever platform offers the best combination of convenience, functionality and value.
I do not believe Revolut will simply replace Switzerland’s established banks. Complex wealth planning, succession, family governance and sophisticated advisory relationships still require expertise and trust.
But Revolut can reset expectations around speed, transparency, pricing and digital usability –and expose institutions that continue to rely on inertia and inherited loyalty.
Be Worried, But Not Paralysed
That may be Revolut’s greatest disruptive power. It does not need to capture every aspect of a client’s financial life. It only needs to become sufficiently useful – and sufficiently trusted – to win an increasing share of it.
Swiss banks should therefore be worried, but not paralysed. Revolut’s advance is a warning that even in the home of private banking, client relationships must now be earned continuously.