Swiss banks promise personal advice, tailored solutions, and an unwavering commitment to their clients. Yet behind the scenes, the reality often tells a different story. In an interview with WealthSummit, Sascha Hostettler, banking expert at Eraneos, explains why so many financial institutions fall short of their promises – and what they must change to remain competitive.
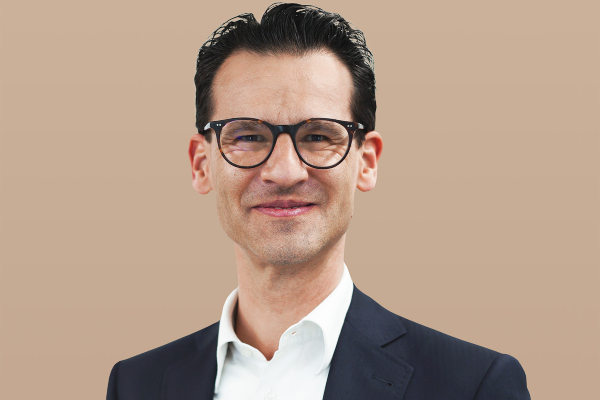
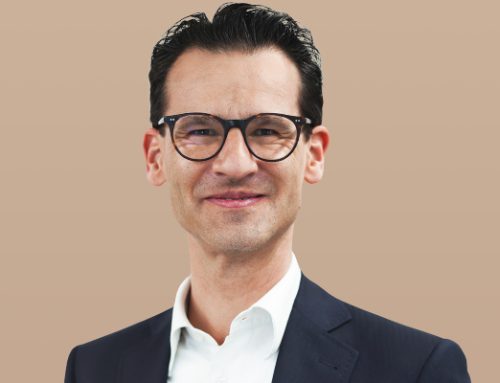
Sascha Hostettler, Head of Sales & Distribution Management, Eraneos (Image: Media Gallery)
Sascha Hostettler, neobanks, digital investment platforms and other fintechs are increasingly offering services once reserved for traditional banks. Are established institutions at risk of losing their most valuable asset – the direct relationship with their clients?
Digital offerings are fast, convenient and inexpensive. Once customers embrace them, they can expand their banking relationships as their needs change. Take Revolut, for example. It already has 1.3 million customers in Switzerland, having added approximately 240,000 in 2025 alone – more than its Swiss competitors Yuh and Neon combined.
In September 2026, Revolut applied to the Swiss Financial Market Supervisory Authority (FINMA) for a Swiss banking licence and announced plans to invest more than 150 million francs. Its planned offerings include salary accounts with Swiss IBANs and deposit protection, as well as pillar 3a retirement savings products.
This means Revolut is moving into precisely those areas where deeper client relationships are built: investments, financing and retirement planning. A sophisticated app alone is not enough. You also need the regulatory framework that allows you to conduct these activities. And this is where speed becomes less important than trust in the relationship.
Banks increasingly encourage clients to manage their finances independently through digital channels. Yet private banks continue to promote personal relationships and bespoke advice. Isn’t that a contradiction?
Not necessarily. A 2024 study by the Institute of Financial Services Zug (IFZ) found that, of the nine most important tasks performed by relationship managers, four either do not require an adviser at all or benefit only marginally from their involvement.
These include opening and closing accounts, changing addresses or powers of attorney, processing payments, and handling services such as online and mobile banking.
«Many relationship managers still have to navigate three to five different systems»
These low-involvement activities are ideal candidates for digital self-service. Clients often carry them out in the evenings or at weekends, when no relationship manager is available anyway. High-involvement matters, by contrast, belong in personal advisory conversations.
The contradiction only arises when both are handled through the same processes. A bank that promises personalised advice while requiring its relationship managers to process address changes is simply failing to deliver on that promise.
Hardly any private bank today operates without an ambitious growth strategy. Why, then, do so many initiatives fail precisely where they matter most – at the client interface?
Many relationship managers still have to navigate three to five different systems to provide a comprehensive picture of a client’s financial situation. Every time they switch systems, their attention shifts away from the client and towards the next data-entry screen.
There is also an inherent conflict between acquiring new clients and deepening existing relationships. Both compete for the relationship manager’s time, yet in most cases only new-client acquisition is measured and rewarded.
Regulatory obligations relating to anti-money laundering and know-your-customer requirements are non-negotiable. They are fundamental to banking. That makes it even more important to identify where advisers can genuinely regain time – particularly in administration and the execution of sales campaigns.
Growth strategies rarely fail because employees do not support them. They fail because there is insufficient capacity. If a bank wants to grow without increasing the time its advisers can devote to clients, it is simply redistributing the same limited working hours.
How must the role of the relationship manager evolve to meet the expectations of tomorrow’s clients?
Fundamental financial needs are not changing. Even the NextGen has five core needs: payments, savings, financing, investments, and retirement planning.
When it comes to financing, investing, and retirement planning, clients will continue to want expert guidance. They will not want to make every decision alone, even with the assistance of an AI agent. At the very least, they will seek a second opinion from a trusted professional.
What is changing is the direction of the advisory process. Today’s technological capabilities make it possible to organise advice around individual client needs, moving from an inside-out approach to an outside-in model.
What does that mean in practice?
It means responding to a client’s needs precisely when they arise – and providing a genuinely individualised service. The relationship manager’s role therefore shifts away from distributing products towards assessing complex situations and facilitating important decisions, whether they concern succession planning, the sale of a business or competing interests within a family.
This requires a more sophisticated set of skills than many relationship managers possess today. And it means that professional training, performance indicators and remuneration systems must evolve accordingly.
Private banks traditionally serve an older clientele whose financial needs are largely established. Younger generations have very different expectations. Are banks facing a growth gap because they fail to understand tomorrow’s wealthy clients?
Baby boomers, those born between 1946 and 1964, are transferring most of their wealth to the next generation, many of whom are themselves already retired or approaching retirement. In other words, another generation of older, wealthy clients is emerging. Looking at age alone does not necessarily reveal a problem.
«The biggest shortcomings lie in the failure to connect different services into a seamless client experience»
Nevertheless, banks must ensure they can reach younger generations and respond to their expectations. Swiss banks are making progress and already satisfy many of their clients’ fundamental needs.
In my view, however, the biggest shortcomings lie in the failure to connect different services into a seamless client experience, the lack of genuine personalisation, processes that are still not fully digitalised, and the absence of integrated platforms built around embedded finance. The problem is therefore less about understanding what clients want and more about actually delivering it.
Banks love to claim that the client is at the centre of everything they do. Yet in reality, products, internal structures and sales targets often dictate what clients are offered. Isn’t that the real problem?
Under the traditional inside-out approach, the bank decides what the client can buy. The business is driven by sales campaigns rather than individual client needs. Given the cost structure of this model, banks have historically been limited to standardised, mass-market offerings.
Today’s technology fundamentally changes that equation. Financial institutions can now focus on clients’ actual needs rather than pushing predefined products. Whether a bank is genuinely client-centric can be assessed in three areas: its performance targets, how it manages sales campaigns, and its remuneration model. Not in its corporate mission statement.
Looking into the crystal ball, artificial intelligence, automated financial services and new digital competitors are set to transform banking fundamentally. What three strategic decisions must Swiss banks make today to remain relevant five years from now?
First, make client needs visible at the point of advice. Data analytics is the means to achieve this. What matters is that relationship managers can immediately identify what has changed in a client’s circumstances when they sit down for a conversation.
Second, let client behaviour determine the advisory approach – not the bank’s product range. The starting point must be what clients actually need, rather than what the institution wants to sell.
Third, align organisational structures and operating processes with the advisory model, not the other way around. Banks that reverse this sequence risk automating a business model that will soon be obsolete.
Which private banks are most likely to succeed in making this transition?
I would not single out particular institutions. Instead, I would look for four distinguishing characteristics.
- An open IT architecture: Banks must be able to deploy and integrate new technologies effectively within their operations.
- Sophisticated data management: Institutions need the ability to conduct genuinely personalised analysis and turn the resulting insights into practical tools for everyone involved.
- A culture of adaptability: Successful banks must actively encourage their people to let go of processes and activities that others can perform more effectively or at lower cost.
- The willingness to let go: This fourth characteristic is also the most difficult to develop. IT architecture and data capabilities can be acquired. A culture that embraces letting go cannot simply be bought.
Sascha Hostettler is Head of Sales & Distribution Management at Eraneos Switzerland. For more than 25 years, he has advised regional banks, cantonal banks and private banks on transforming their market strategies, client relationships and business models. His professional experience spans roles as a board director, CEO, executive management member, consultant and lecturer. He also serves as an expert adviser at the Institute of Financial Services Zug (IFZ) at Lucerne University of Applied Sciences and Arts. He combines hands-on banking and corporate governance experience with extensive expertise in digital transformation, market development, client relationships, and cyber risk management.