Revolut is unlikely to turn Swiss private banking upside down. But institutions offering little more than custody, trade execution and a quarterly phone call may have genuine reasons to worry. For them, the neobank could become a serious competitive threat, warns Charles-Henry Monchau in his analysis for WealthSummit.
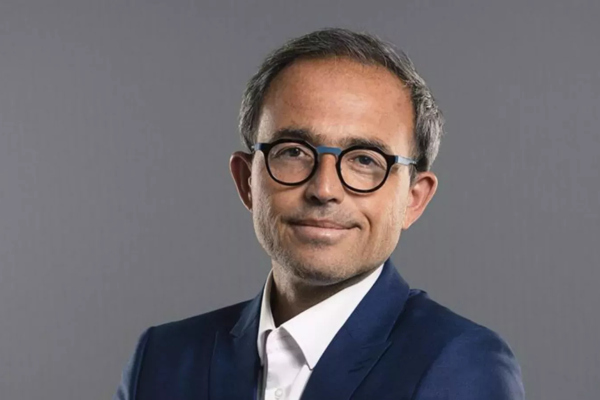
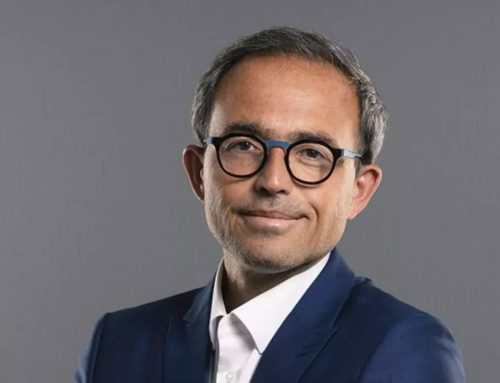
Charles-Henry Monchau, Chief Investment Officer (CIO) and Member of the Executive Committee at Bank Syz (Image: media release).
This article is published as part of WealthSummit’s editorial partnership with the Swiss financial news platform Allnews.
Revolut has applied for a Swiss banking licence from the Swiss Financial Market Supervisory Authority (FINMA) and plans to invest more than 150 million francs in expanding its operations in Switzerland.
The neobank already claims approximately 1.3 million customers in the country, representing market penetration of around 24 percent. Over the next two to three years, it aims to increase that figure to more than 40 percent. At first glance, this looks primarily like a retail banking story: Swiss IBANs, salary accounts and eBill. But Revolut’s ambitions extend considerably further.
For Swiss private banks, the question is therefore whether a fully licensed, well-capitalised and technology-driven neobank – already present in the pockets of roughly a quarter of the population – will eventually compete not only for their existing clients, but, more importantly, for their children.
What a Swiss Banking Licence Would Change
Until now, Revolut has served the Swiss market on a cross-border basis through Revolut Bank UAB, its Lithuanian-licensed banking entity. In Switzerland, it maintains a representative office but does not hold a domestic banking licence. This structure has significantly constrained its product offering.
As a result, Revolut has been unable to provide conventional Swiss salary accounts or Swiss franc-denominated investment accounts. Customers could not have their salaries paid directly into a Revolut account, limiting the app’s practical appeal largely to foreign-currency payments and travel-related spending.
A FINMA licence would remove many of these restrictions. In an initial phase, Revolut is expected to introduce conventional Swiss banking services, including Swiss IBANs, salary accounts, eBill, broader payment acceptance and access to the Swiss deposit protection scheme. Pillar 3a pension products and integration with TWINT are also among its planned services. Meanwhile, the company intends to expand its Swiss workforce from approximately 30 employees to nearly 100 by the end of 2027.
Could Private Banking Be Next?
A Swiss banking licence would provide Revolut with the foundations to establish itself gradually in the affluent and lower high-net-worth (HNW) segments. The second phase of its expansion could therefore become particularly relevant for traditional wealth managers.
The United Kingdom offers a glimpse of what may lie ahead. There, Revolut is planning private banking services for customers able to deposit at least 500,000 pounds. The company has also obtained regulatory permissions from the UK’s Financial Conduct Authority (FCA) covering leveraged products, portfolio management and private wealth services, including discretionary portfolio management and investment advice for retail, professional and wealthy clients.
At the same time, Revolut is adding a more personal dimension to its business model. The company has been recruiting a head of relationship management to establish and lead a team of client advisers. It is also strengthening ties with major investment product providers. According to media reports, Revolut has held discussions with Blackstone about integrating investment products into its planned private banking offering. In parallel, it is building its own private markets team.
Applied to Switzerland, the potential model is relatively straightforward: a Swiss franc current account, Pillar 3a pension savings, a brokerage platform offering fractional shares, ETFs and cryptocurrencies, complemented by discretionary asset management at a fraction of traditional banking fees.
Lombard lending, selected private markets investments from established providers and a dedicated relationship manager accessible directly through messaging could follow. All these services would be integrated into a single app, with account opening completed in minutes and transparent pricing throughout.
The Real Product Is the Client Experience
It is not the individual products that should worry established private banks. Almost all of them are already available from private banks in Geneva and Zurich.
What Revolut is really selling is the experience surrounding those products: almost instantaneous account opening, a real-time overview of personal wealth, no mountains of paperwork, no waiting for a relationship manager to return a call – and the same interface for a travel card holding 5,000 francs as for an investment portfolio worth 5 million francs.
In doing so, Revolut is increasingly turning banking administration and securities execution into standardised services. Crucially, the company also operates at a scale that allows it to invest continuously in its technology platform. According to its own forecasts, Revolut expects revenue of approximately $9 billion and profits of $3.5 billion in 2026.
That financial firepower is matched by an already substantial customer base. A growing proportion of Swiss private banking clients – and particularly their children – already use Revolut in everyday life.
Expectations of digital banking are therefore increasingly shaped by an app that has established a significant presence in Switzerland. Once that same app can also accommodate a discretionary wealth management mandate, clients will inevitably begin asking an uncomfortable question: What exactly are they paying traditional banks fees of more than 1 percent for?
Which Banks Are Most Exposed?
Not all private banks face the same degree of disruption. The greatest risk lies with institutions whose value proposition has gradually been reduced to custody, trade execution, and a quarterly telephone conversation.
- Institutions Serving the Mass-Affluent and Lower HNW Segments
Clients with assets ranging from 250,000 francs to 2 million francs are frequently served through simplified advisory models or standardised discretionary mandates.
They fit Revolut’s target profile almost perfectly: digitally savvy, price-sensitive and often without any immediate need for sophisticated cross-border wealth structuring or family governance.
In the UK, the mass-affluent segment is estimated to represent approximately 9 trillion pounds in wealth – more than the ultra-high-net-worth and retail segments combined. Revolut’s proposed minimum threshold of 500,000 pounds offers a clear indication of the clientele it intends to attract.
- Swiss Banks Focused on Domestic Clients and Undifferentiated Investment Services
Cantonal and regional banks, along with certain private banks, have traditionally built their businesses around local clients, personal proximity and trust.
A Revolut equipped with a Swiss banking licence, Swiss IBANs, deposit protection and Pillar 3a products would compete directly on many of these attributes – but potentially at significantly lower cost.
- Banks Whose Digital Transformation Stopped at Online Banking
When the client experience still revolves around PDF account statements, handwritten signatures and onboarding procedures that take weeks, comparisons with Revolut become particularly unforgiving.
Even clients who would never consider transferring their entire wealth to a neobank cannot fail to notice the difference.
- The Generational Wealth Transfer
Perhaps the greatest risk is not the immediate loss of existing clients, but the impending transfer of wealth to the next generation.
Heirs who have managed their financial lives through Revolut for a decade have little reason to remain automatically loyal to their parents’ relationship manager.
If an inherited investment portfolio can simply be transferred into the app they already use every day, the incumbent bank could lose the relationship before it has even had an opportunity to establish one with the next generation.
At the upper end of the wealth spectrum, however, Revolut’s model is considerably less compelling.
Ultra-high-net-worth clients and internationally complex wealth structures require booking platforms across multiple jurisdictions, trust and succession planning, bespoke financing against illiquid assets, direct access to portfolio managers, and an institution whose financial strength, discretion and stability have been demonstrated over decades.
Revolut’s regulatory track record also warrants consideration. Obtaining its UK banking licence took three years, partly because of concerns surrounding its global compliance infrastructure. FINMA can be expected to apply similarly rigorous scrutiny – an issue that particularly demanding wealth management clients will follow closely.
How Can Swiss Private Banks Defend Their Competitive Advantage?
Responding to Revolut does not mean trying to beat the neobank at its own game.
Traditional private banks are unlikely to win a technology or design contest against a platform with approximately 80 million users. Their real competitive advantage lies in services that a financial super-app cannot easily replicate at scale.
- Reduce Fees for Commoditised Services and Revalue Advice
Custody, trade execution and basic reporting are increasingly becoming low-value-added services. Institutions that continue to derive a substantial share of their margins from these activities are particularly vulnerable.
By contrast, banks that transparently charge for advice, portfolio construction, wealth structuring and access to differentiated investment opportunities offer a value proposition that is considerably harder for Revolut to reproduce at scale.
- Make Personal Relationships the Core Offering – and Digitalise Everything Around Them
Relationship managers should spend their time on decisions requiring experience, judgement and specialist expertise: asset allocation in a changing macroeconomic environment, succession planning, liquidity management or the sale of a family business.
They should not be spending that time on administrative tasks.
Delivering this model requires less visible but essential infrastructure: automated onboarding, consolidated reporting across multiple custodian banks, electronic signatures and a banking app that does not compare unfavourably with Revolut.
The objective is not necessarily to build the best banking app on the market. It is to ensure that clients have no compelling reason to prefer someone else’s.
- Own the Intellectual Capital: Research and Investment Expertise
A genuine investment philosophy, a clearly defined CIO-led asset allocation process and rigorous due diligence in private markets are considerably more difficult for a digital platform to replicate.
Research, thematic investment convictions and a distinctive view of financial markets form part of a private bank’s intellectual capital.
These strengths need to be published, explained and distributed through the channels clients actually use. Above all, they must translate into tangible portfolio decisions.
- Differentiate Through Access, Not Product Breadth
Co-investments, club deals, private credit, pre-IPO opportunities, selected hedge funds and bespoke structured products depend on relationships, significant investment thresholds and specialised expertise.
A super-app can distribute feeder funds. A strong private bank, by contrast, can provide direct access to carefully selected investment opportunities.
That distinction matters – particularly to sophisticated investors seeking more than standardised market exposure.
- Engage the Next Generation Before the Wealth Transfer
Banks that wait until an inheritance takes place before establishing relationships with their clients’ children and grandchildren are taking a considerable risk.
The next generation needs to be engaged early, with low or even no minimum entry thresholds, financial education and a digital experience they genuinely want to use.
The focus should be on building a lasting relationship with the entire family, rather than simply managing the parents’ existing investment mandate.
- Capitalise on Financial Strength and the Swiss Banking Brand
Balance sheet strength, decades of stability, credible supervision and a deeply embedded culture of discretion are valuable assets that an institution with only a few years of banking history cannot easily reproduce.
But private banks must communicate these strengths in ways that resonate with contemporary clients.
A prestigious brand alone is no longer sufficient when the accompanying client experience feels outdated.
- Use Partnerships and AI to Narrow the Cost Gap
Banks that cannot develop every technological capability in-house should increasingly acquire solutions or form strategic partnerships.
Potential areas include core banking modernisation, AI-powered client assistants and the automation of know-your-customer (KYC) processes.
The structural cost disadvantage between a traditional private bank and a neobank will not disappear on its own.
A cost-income ratio above 70 percent will become increasingly difficult to justify when a competitor can deliver many standardised services through a substantially leaner operating model.
Conclusion: Revolut Is Accelerating a Transformation Already Under Way
A Swiss banking licence would allow Revolut to establish itself gradually in the affluent and lower HNW segments. It would also intensify pricing pressure on standardised banking services while raising expectations of the digital client experience.
The institutions most exposed are those whose value proposition rests primarily on custody fees and the strength of their brand.
Yet private banking retains competitive advantages that cannot easily be replicated or scaled: the quality of advice and professional judgement, access to differentiated investment opportunities, expertise in complex wealth structuring and trust built over many years.
Banks that successfully reinforce these strengths while modernising their digital infrastructure will continue to have a compelling case for the value they deliver.
For institutions already struggling to justify their fees, however, Revolut is simply accelerating a transformation that began long ago.
Charles-Henry Monchau is Chief Investment Officer (CIO) and a Member of the Executive Committee at Bank Syz.