
Image: UBS
UBS’ Next Big Risk: Bankers Who May Walk Away
Swiss banking giant UBS has survived the integration of Credit Suisse remarkably well. But I suspect its greatest challenge may only be beginning – and this time, it has less to do with capital requirements than with the people who manage its wealthiest clients.
The numbers look reassuring. According to its third-quarter results published on Wednesday, UBS Global Wealth Management attracted an impressive $55.1 billion in net new assets, bringing invested assets to nearly $5 trillion. Group net profit reached $2.69 billion, while the integration of Credit Suisse remains on track for substantial completion by year-end. Yet these impressive figures conceal a potentially uncomfortable reality: client loyalty today does not guarantee banker loyalty tomorrow.
As Geneva-based executive search specialist Gil M. Chalem argues, the completion of Credit Suisse’s client migration removes one of the strongest incentives for relationship managers to remain at UBS. Deferred compensation, integration uncertainty and client disruption previously discouraged departures. Those constraints are gradually disappearing.
Window of Opportunity
I believe 2027 could therefore become a defining year for Switzerland’s private banking industry. Independent wealth managers, family-owned banks and ambitious competitors may find themselves facing an unusually attractive recruitment market.
Meanwhile, the unresolved debate over UBS’s capital requirements adds another layer of uncertainty. Even discussions about relocating its headquarters undermine one of the bank’s traditional selling points – its Swiss identity.
Real Test of Loyalty
But recruiting bankers is not the same as acquiring their clients. Relationships built around UBS’s lending capabilities, international infrastructure and investment platform may prove surprisingly difficult to transfer. For me, the larger question is whether UBS can transform integration success into lasting employee loyalty. Its formidable scale remains an advantage, but size alone cannot guarantee commitment.
The Credit Suisse takeover tested UBS’s ability to retain assets. The next chapter may test something more consequential: its ability to retain the people behind them.
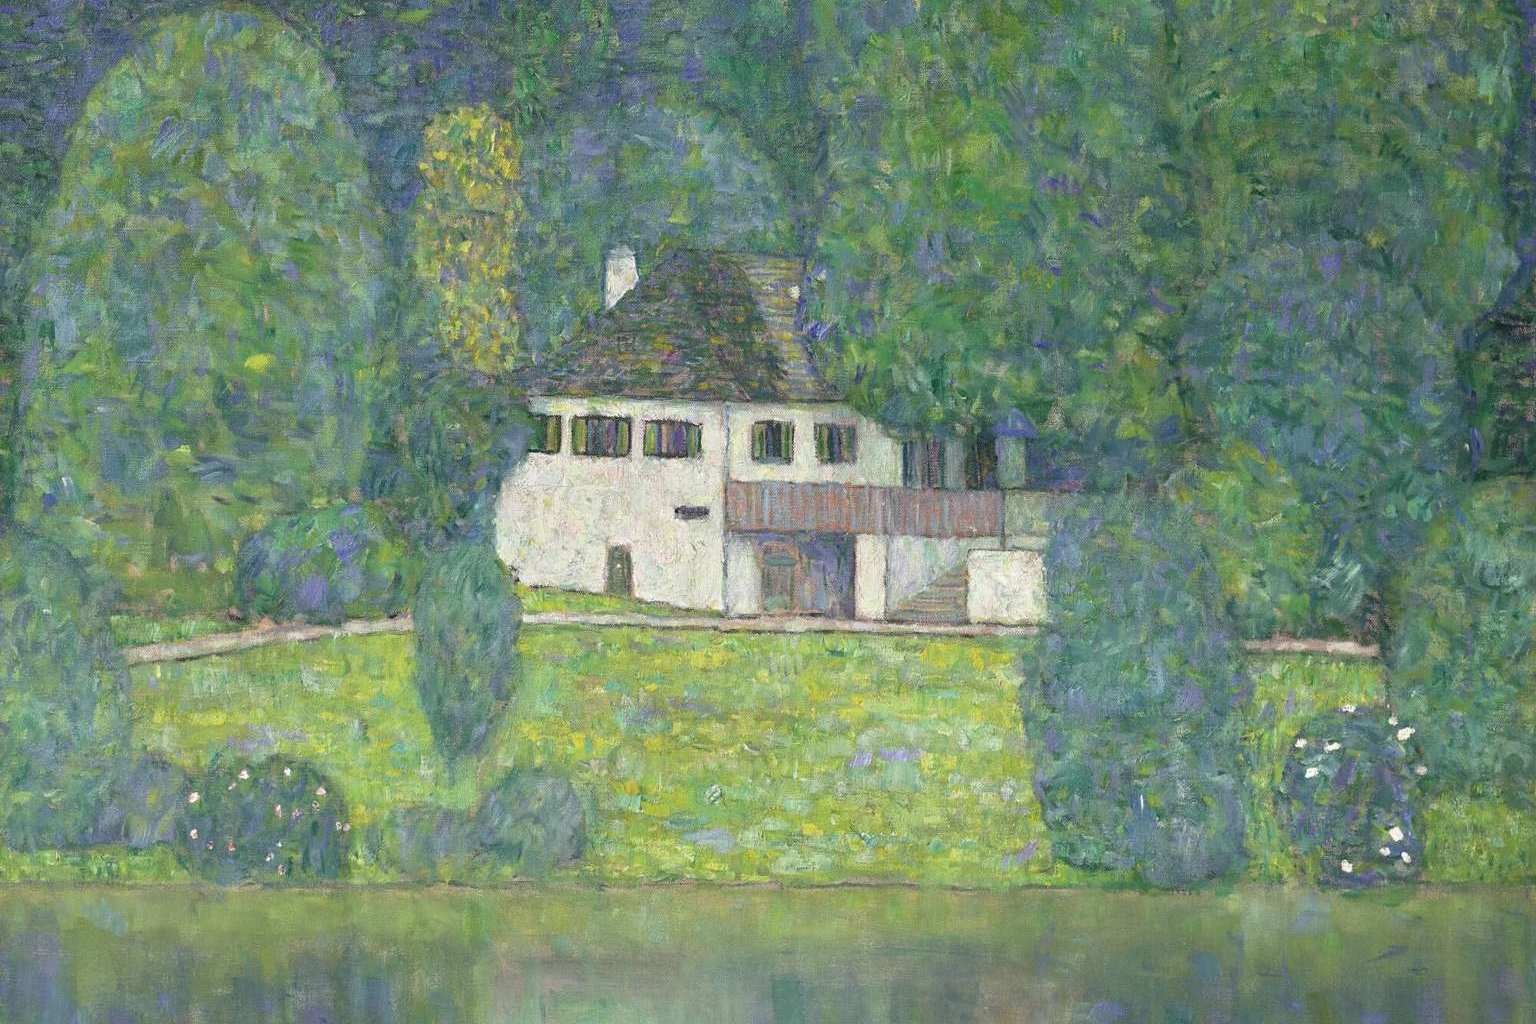
Image: Christie's Media
The Art of Getting Rich: What a $80 Million Klimt Reveals About Wealth
A painting bought for $14.7 million in 1997 could soon fetch $80 million. I find this remarkable – not merely as a testament to Gustav Klimt’s artistic legacy, but as a revealing illustration of how wealth, scarcity and prestige interact in the global art market.
On November 17, Christie’s will auction «Litzlbergkeller», a landscape painted in 1915-16, with an estimate of $60 million to $80 million. The painting has remained in private hands for almost three decades. Its previous sale established a Klimt auction record; today, his record stands at $236.4 million.
Interestingly, the painting was commissioned by Otto Primavesi, an Austrian banker and art patron. More than a century later, his investment in artistic creativity has become an extraordinary store of wealth.
When Scarcity Commands a Premium
I would caution, however, against confusing spectacular auction prices with predictable investment returns. At $80 million, the painting would have appreciated approximately 5.6 percent annually since 1997, before inflation, insurance, transaction costs and taxes.
The art market also presents a peculiar paradox: while masterpieces command astronomical prices, most artworks remain illiquid, difficult to value and expensive to maintain. Christie’s has guaranteed the Klimt’s sale – itself an indication of how financial engineering increasingly shapes the market for trophy assets.
More Than an Investment
For wealth managers, the implications extend beyond portfolio diversification. Art combines financial value with cultural identity, personal prestige and intergenerational legacy; qualities that conventional investment products struggle to replicate. Yet I wonder whether today’s extraordinary valuations reflect artistic appreciation or the growing concentration of global wealth.
Perhaps the most fascinating aspect of the Klimt auction is not what the painting is worth – but what its price tells us about the people wealthy enough to own it.
Image: Adobe Stock
Midterm Elections: Preparing For Political Turbulence
Fund managers are hoarding cash, buying downside protection and reconsidering their exposure to equities ahead of America’s November 3 midterm elections. Yet I suspect the greatest danger lies not in the election result itself, but in what investors may be overlooking.
According to the «Australian Financial Review», institutions including Schroders and Pictet Asset Management are adopting defensive positions. Swiss-based Pictet estimates that protecting against a 10 percent S&P 500 decline over the coming month would cost approximately 0.2 percent of the index’s value. Insurance, apparently, remains relatively inexpensive.
Meanwhile, Polymarket assigns roughly a 66 percent probability to Democrats winning both chambers of Congress. Interestingly, Amundi still considers a divided Congress its most likely outcome.
Gridlock Illusion
I find Wall Street’s traditional preference for political gridlock increasingly questionable. Investors often welcome legislative paralysis because it limits disruptive policy changes. But in today’s environment of elevated interest rates, geopolitical tensions, and fiscal pressures, political paralysis could become a liability rather than a blessing.
More importantly, a constrained White House might rely increasingly on executive powers, particularly tariffs. Unlike legislative proposals, such measures can surprise markets with little warning.
Beyond Election Night
History offers reassurance. Wells Fargo notes that the S&P 500 has risen during the 12 months following every US midterm election since World War II. But historical patterns are not investment guarantees. For wealth managers, I believe the lesson is straightforward: political forecasts should never substitute for disciplined risk management. Holding liquidity and purchasing protection may be sensible, but neither eliminates uncertainty.
The real question is not who wins Congress next Tuesday. It is whether financial markets are prepared for how Washington behaves afterward.
Image: Adobe Stock
Wall Street Wants Asia’s Wealth – Should Swiss Banks Be Worried?
For decades, Swiss private banks have regarded Asia as one of their most promising growth markets. Now Wall Street is intensifying the competition. I believe Goldman Sachs’ latest expansion plans reveal something important: the battle for Asian wealth is increasingly about capabilities, not merely client relationships.
According to Hong Kong-based «South China Morning Post», Goldman Sachs is accelerating recruitment in Singapore, Hong Kong and Australia. Nishi Somaiya, its global co-head of wealth management, reports double-digit growth in the bank’s Asian wealth business over recent years. Demand is being driven partly by wealthy families seeking diversification into US assets and entrepreneurs benefiting from the artificial intelligence boom.
What strikes me is that Goldman Sachs is recruiting not only relationship managers but also trading and lending specialists. This suggests a strategy built around combining investment banking expertise with sophisticated wealth management.
Swiss Advantage Is No Longer Enough
Traditionally, Swiss private banks have competed through discretion, stability, international diversification and personal advice. These remain formidable strengths. But increasingly sophisticated Asian clients also want access to private markets, structured financing, technology investments and global investment opportunities.
American institutions can potentially leverage their capital markets expertise and extensive corporate networks to meet these demands. I see this as a serious competitive challenge, particularly for Swiss banks whose business models remain heavily dependent on conventional portfolio management.
Relationships Still Matter – But Differently
Yet I would not underestimate Switzerland’s position. Wealthy Asian families still value institutional stability, independent advice and long-term relationships. The real question is whether Swiss private banks can combine these traditional strengths with the capabilities offered by their American competitors.
Goldman Sachs is not simply recruiting bankers in Asia. It is challenging the very definition of what a private bank must deliver. Will Switzerland respond – or surrender the initiative?
Image: Pexels
When Safe Havens Become the Riskiest Bets
Gold and Bitcoin were supposed to protect investors from uncertainty. Instead, both are languishing at the bottom of the 2026 performance rankings. I believe this extraordinary reversal raises an uncomfortable question about what investors consider safe.
According to Charlie Bilello, chief market strategist at Creative Planning, Bitcoin had lost 7.3 percent and gold 7.5 percent by October 23. Never before, in his records dating back to 2011, have these two assets occupied the bottom positions simultaneously.
Meanwhile, commodities have gained 52.5 percent, US large-cap equities 12.3 percent, and even short-term Treasury bills have delivered 2.9 percent. The irony is striking: investors seeking refuge from instability have watched supposedly defensive assets underperform cash.
Price of Protection
I find the parallel decline particularly revealing because gold and Bitcoin represent fundamentally different investment propositions. Gold derives credibility from centuries of monetary history. Bitcoin promises independence from traditional financial institutions. Yet neither offers income – an increasingly painful disadvantage when inflationary pressures keep interest rates elevated.
Gold’s reversal is especially dramatic following its 63.7 percent surge in 2025. Bitcoin, meanwhile, remains approximately 35 percent below its October 2025 peak. As BeInCrypto reports, both assets are struggling against changing monetary expectations.
Lesson for Wealth Managers
For private banks, I see a broader lesson. Diversification cannot be reduced to accumulating fashionable alternatives. Assets with different narratives can become vulnerable to the same macroeconomic forces.
History may ultimately vindicate both investments. But their simultaneous weakness exposes a dangerous assumption: that an asset’s reputation as protection guarantees protection when it matters. Perhaps the greatest portfolio risk is not volatility itself, but misplaced confidence in what supposedly protects us from it.