Singapore’s financial center currently has a more coherent strategy because it treats wealth management as a national growth industry. Switzerland still tends to regard it as an established strength that must primarily be protected and regulated.
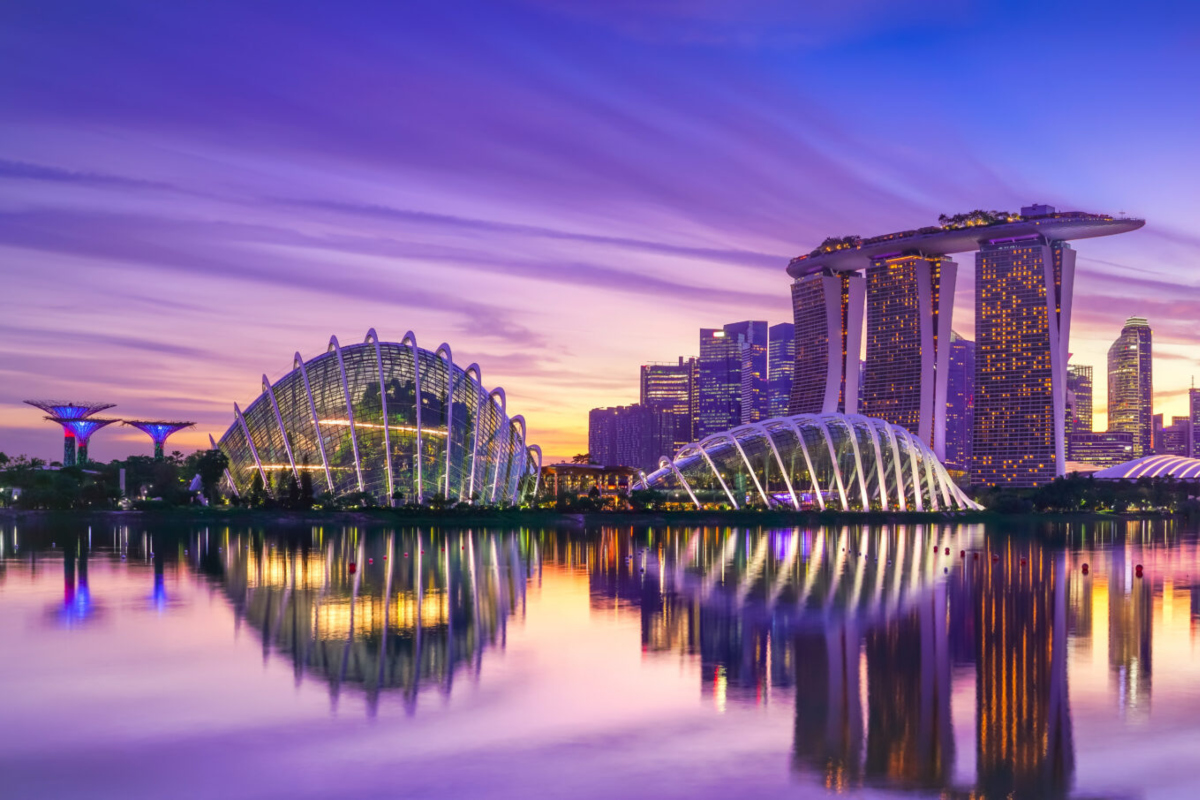
Singapore’s Marina Bay (Image: Adobe Stock)
Singapore coordinates all the essential components: tax policy, immigration, regulation, public investment, technology, talent development and international promotion. Its recent package for fund managers is a good example: tax exemptions, a hedge-fund investment programme and easier visa rules all serve the same objective: attracting firms, capital and decision-makers.
The Monetary Authority of Singapore (MAS) therefore acts not only as a regulator, but also as an architect of the financial ecosystem.
Singapore Builds While Switzerland Defends
Switzerland operates differently. Responsibility is distributed among the federal government, FINMA, the cantons, industry associations and individual institutions. That decentralisation has advantages, but it rarely produces a single strategic direction.
Since the collapse of Credit Suisse, much of the debate has understandably concentrated on capital requirements, supervision and systemic risk. Necessary as that is, it leaves Switzerland appearing defensive while Singapore is building for growth.
The Comfort of Accumulated Success
Switzerland also suffers from the comfort of accumulated success. It still manages enormous volumes of international wealth and remains associated with stability, expertise and discretion. But a large stock of existing assets does not guarantee future inflows.
Singapore is positioning itself for newly created Asian wealth, internationally mobile entrepreneurs and families establishing professional family offices.
Five Priorities for a New Swiss Strategy
A credible Swiss strategy should, in my view, rest on five priorities:
1. Redefine Swiss Confidentiality
Switzerland cannot return to traditional banking secrecy. It can, however, become the world’s most trusted jurisdiction for legally compliant financial privacy, cybersecurity and responsible data governance. The controversy surrounding the beneficial-ownership register shows how important this distinction has become.
2. Become the Leading Centre for Complex Wealth
Switzerland should compete less on portfolio management alone and more on the difficult issues surrounding wealth: succession, family governance, cross-border structuring, entrepreneurial liquidity events, philanthropy and private-market holdings. These are areas in which human judgement still matters, and fees are less easily commoditised.
3. Build an Open Wealth-Management Ecosystem
Banks, EAMs, family offices, fintechs, lawyers and other specialists should be able to collaborate through interoperable platforms. Future clients will use several providers. Switzerland’s opportunity is therefore not necessarily to «own» every client relationship, but to become the most trusted orchestrator of complex wealth.
4. Create a Serious Policy for Talent and Innovation
Switzerland needs easier access to specialists in AI, digital assets, cybersecurity and international wealth planning. Regulation should also allow controlled experimentation with tokenisation, digital custody and AI-supported advice. Singapore connects innovation policy directly with financial-centre policy; Switzerland largely treats them as separate subjects.
5. Develop a National Strategy for the Next Generation of Wealth
This strategy should address both inherited and newly created wealth. NextGen clients expect international access, digital convenience, attractive investment opportunities and specialist advice without becoming dependent on a single institution. Switzerland should design its proposition around these behaviours rather than around traditional client segments.
From Preserving Wealth to Attracting It
The fundamental difference is one of posture: Singapore asks how it can attract the next trillion. Switzerland too often asks how it can preserve the trillions already there. A successful Swiss strategy must do both.
Switzerland does not need to imitate Singapore. Its stronger proposition would combine Swiss stability and depth with a far more open, technologically capable, and client-centered ecosystem. Its future lies not in being merely the safest place to store wealth, but in becoming the best place to structure, govern, and deploy it.